
Loan Disbursement: How Your Loan Actually Lands in Your Account (And Why It Sometimes Feels Like Watching Paint Dry)
Let’s be honest—waiting for your loan to hit the bank feels like suspense in a Bollywood thriller. One minute, you’re dreaming of a shiny new car or college abroad; the next, you’re refreshing your account every five seconds. So, what really happens between “loan approved” and “money in my hand”? Buckle up—this is your behind-the-scenes look at loan disbursement, with hacks, human stories, and plenty of “a-ha!” moments.
What Is Loan Disbursement?
Think of loan disbursement as the grand finale of your borrowing journey. It’s when the lender takes the approved loan amount and actually transfers it—either to your bank account, a vendor (like a car dealer), or directly to a college or builder, depending on your loan type.
In other words, it’s payday (well, you have to pay it back, but still, it’s a thrill).
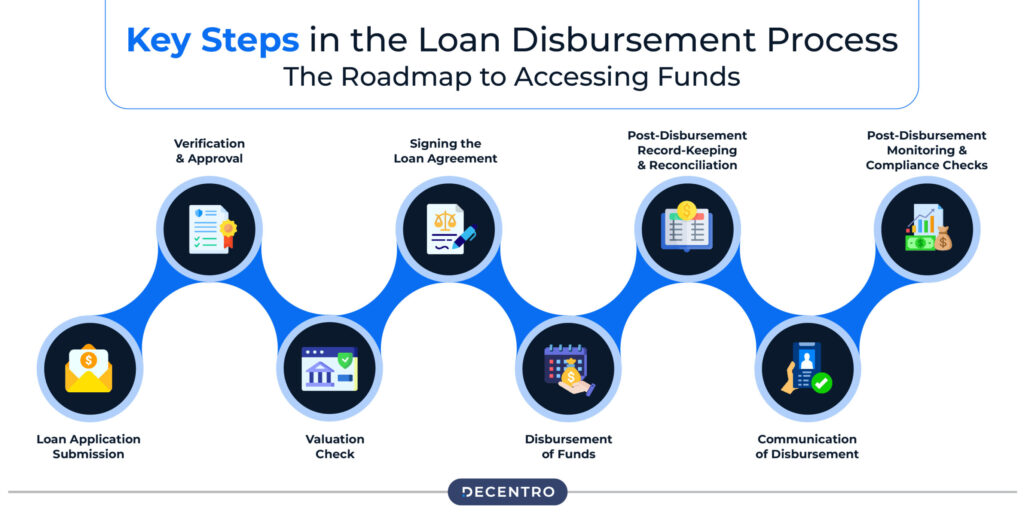
The Typical Loan Disbursement Process (2025 Edition)
Honestly, loan disbursement is like a relay race—with a marathon of paperwork and approvals. Here’s how the baton is passed:
1. Application
You fill out the loan form—online or at the branch. It’s a digital world, but some lenders still love paperwork.
2. Document Check & Verification
Lenders verify everything—your identity, address, financials. For property loans, be prepared for document marathons.
3. Credit Assessment & Loan Approval
Your credit history gets the microscope treatment. Good score? Fast lane. Bad score? Expect some speed bumps.
4. Loan Sanction Letter
If you pass all checks, the lender issues a sanction letter—laying out the loan amount, rate, tenure, fees, and other fine print. Read every word, trust me!
5. Agreement & Legalities
You sign the agreement, sometimes submit post-dated cheques or set up ECS mandates. Home and business loans might mean more legal steps here.
6. Final Approval & Disbursement Decision
Double-checks, compliance reviews, and sometimes field visits—especially for big loans.
7. Disbursement
Drumroll—the loan is credited via NEFT, RTGS, IMPS, or cheque—often directly to your account, vendor, or institution. In phased loans (like home or education), amounts may be disbursed in tranches as you progress with your project or studies.
Disbursement Timelines: How Fast Does the Money Arrive?
Speed depends on loan type, lender, and your paperwork game:
| Loan Type | Disbursement Time (Typical) |
|---|---|
| Personal Loan | 24 hours–7 days |
| Home Loan | 5–15 days |
| Car Loan | 1–5 days |
| Business Loan | 3–15 days |
| Education Loan | 7–15 days |
| Gold/Instant Loan | Few hours–1 day |
Digital lenders and fintechs can pull off “instant loans”—sometimes in under an hour. Traditional banks tend to be less caffeinated.
Common Causes for Disbursement Delays
-
Missing or wrong documents (seriously, triple-check your forms!)
-
Low credit score or unclear repayment history
-
Unforeseen verification issues or holidays/bank closures
-
Lender-specific processing timelines (some just take their sweet time)
By the way, if it’s month-end, quarter-end, or festival season—expect some added “waiting game” fun.
Personal Anecdote: The Day My Loan Finally Arrived
Flashback to my friend’s home loan disbursement. We were camped at the builder’s office, refreshing the SMS inbox every few minutes. Snacks were ordered, jokes made, panic set in—and just as we were about to give up, ping! The funds arrived, just in time to bag an early bird offer.
Lesson? Bring snacks (and patience).
Pro Tips to Speed Up Your Loan Disbursement
-
Go digital: Online KYC and digital agreements can shave days off the process.
-
Submit complete paperwork: Don’t leave blanks or send fuzzy photocopies.
-
Monitor your credit: A solid score makes things smooth.
-
Chase, but politely: Check in with your loan manager, but no need to go full stalker.
-
Pick a lender with a reputation for fast processing: Check reviews and ask around.
How Is Disbursement Different for Each Loan Type?
-
Personal & Car Loans: Lump sum to your account or dealer. Fastest when pre-approved.
-
Home Loans: Phased release—each installment after property checks, builder progress, or proof of own contribution.
-
Education Loans: Direct to college/university (sometimes in stages—per semester/year).
-
Business Loans: Often depends on business milestones or project progress.
Loan Disbursement FAQs (Optimized for Snippets)
What does loan disbursement mean?
It’s the process by which the lender releases the approved amount—either to you, a vendor, or institution.
How long does loan disbursement take in 2025?
Personal loans can disburse in as little as 24 hours, while home and education loans may take up to 15 days, depending on lender policies and documentation.
Does disbursement happen after signing the loan agreement?
Yes—once you sign and legal checks are done, the lender initiates the transfer.
Can loan disbursement be delayed?
Yes—due to incomplete paperwork, credit issues, public holidays, or internal bank processing times.
Is loan disbursement always full amount at once?
No—home and education loans can be disbursed in tranches as per project or semester progress.
What to Watch Out For
-
Always double-check the account number/beneficiary details. You don’t want your study abroad funds ending up in Timbuktu.
-
Review disbursement terms—lump sum or phased, direct credit or via third parties.
-
Ask about disbursement charges or fees—sometimes lenders sneak in one last surprise.
Myths and Truths
-
Myth: Disbursement is always instant.
Reality: Even in 2025, some things still take time. -
Myth: You can redirect funds anywhere you want.
Reality: Lenders often restrict end use, especially for home and education loans. -
Myth: Only banks can disburse fast.
Reality: Fintech NBFCs are often faster. Digital FTW.
Final Thoughts: From Dream to Reality (or, Why Patience Pays)
Loan disbursement may sound boring, but it’s your final hurdle between “I wish” and “I did it.” Stay sharp, watch the docs, and partner with lenders who value your time. With the right prep, you can go from application to disbursement in record speed.
Call to Action
Freshly disbursed and living your dream? Hit a snag in the process that made you facepalm? Share your best (or worst!) loan disbursement war story in the comments.
And if this guide saved you time, hand it off to a friend—no one should be left hanging when their dream is just one “disbursement” away!