
Loan Journal Entry: The Only Guide You’ll Ever Need (Explained Like You’re Talking to a Friend)
Ever stared at your accounting books and felt like they were silently judging you? Trust me, I’ve been there.
You open your ledger, see numbers everywhere, and suddenly start questioning every life choice that led you to this moment.
But here’s the fun twist — once you understand loan journal entries, the whole intimidating aura disappears. It’s like learning the cheat codes to a game you’ve been struggling with for months.
So today, let’s break down everything about loan journal entries in the most relatable, informal, and downright friendly way possible. If you want expert-backed insights delivered in simple, natural, storytelling language — you’re in the right place.
By the way, grab a cup of chai or coffee… this is going to be fun.
Let’s dive in.
What Is a Loan Journal Entry? (Explained in One Simple Line)
A loan journal entry is an accounting record that tracks money borrowed or repaid by a business or individual.
See? Not rocket science.
When you take a loan, you record the liability.
When you repay it, you record the payment.
When interest hits like unwanted rain during a wedding, you record that too.
Why Loan Journal Entries Matter (Even if You Pretend They Don’t)
Honestly, I used to think, “Yaar, journal entries are just paperwork.”
But nope — they’re the unsung heroes keeping your financial records clean, accurate, and safe from auditor-level scolding.
Loan journal entries help you:
-
Track borrowed funds
-
Maintain accurate liabilities
-
Understand interest expenses
-
Prepare for tax filings
-
Boost your business creditworthiness
-
Avoid embarrassing “Wait, how much do I owe?” moments
Think of them as the GPS for your loan activities. Skip them, and you’re driving blindfolded on a highway.
Types of Loan Journal Entries (Based on Real-life Scenarios)
Loans come in various shapes and moods, just like people. Because of that, their journal entries vary too.
Here are the common types:
1. Loan Received Entry
When you borrow money from the bank.
2. Loan Repayment Entry
When you pay the EMI — principal + interest.
3. Loan Interest Accrued
Interest that accumulates over time.
4. Loan Interest Paid
Actual payment of interest.
5. Loan Prepayment Entry
When you pay the loan early (and feel like a financial superhero).
Story Time: My First Loan Journal Entry Mistake (Learn From My Pain)
A few years ago, I took a small business loan. Feeling all grown-up, I proudly entered:
Later I realized…
I recorded only the principal.
Forgot the interest.
Forgot the processing fees.
Forgot the insurance component.
Basically, I forgot everything except my own confidence.
And guess what?
The accountant looked at me like I’d just asked whether Earth is flat.
That day I learned:
A correct loan journal entry is more than just debit-credit… it’s about capturing the complete financial picture.
Loan Received Journal Entry (With Simple Examples)
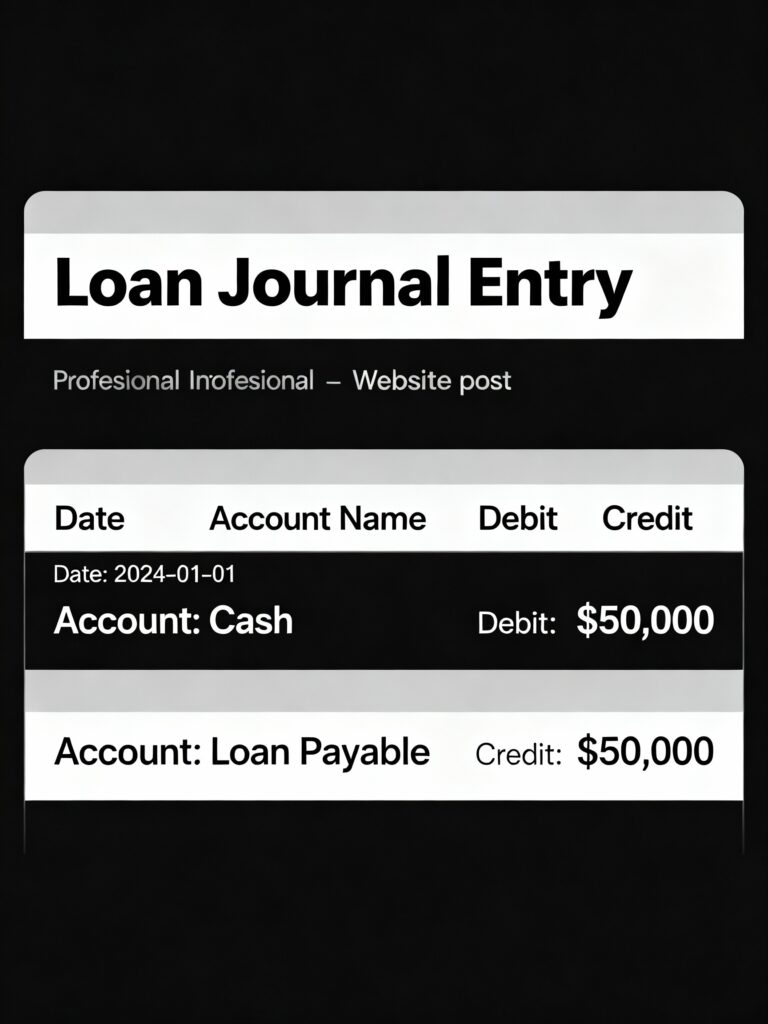
The moment you receive loan money, it increases your cash/bank balance and creates a liability.
Journal Entry:
Why?
-
Debit = increase in assets
-
Credit = increase in liability
Example:
You receive ₹5,00,000 loan.
Simple. Clean. Beautiful.
Loan Interest Journal Entry (Because Interest Never Stops, Right?)
Interest is like that one clingy friend — always coming back.
You record interest accrued even if it’s not paid yet.
Journal Entry for Interest Accrued:
When You Pay the Interest:
OR, If Interest Is Paid Immediately:
Easy-peasy.
Loan EMI Payment Journal Entry (EMI = Principal + Interest)
EMIs feel like emotional damage every month, but accounting them doesn’t have to be.
EMI usually has two parts:
-
Principal payment — reduces loan amount
-
Interest payment — expense
EMI Payment Entry:
Example:
Total EMI = ₹15,000
Interest = ₹4,000
Principal = ₹11,000
Your loan reduces, your interest is recorded, and your bank balance cries a little.
Loan Prepayment Journal Entry
Prepayment = paying more than required.
If prepayment includes charges:
Loan A/C ................. Dr.

Prepayment Charges A/C .. Dr.

    To Bank A/C
Processing Fees & Other Charges Entry
Banks love their fees, right?
Processing fee is usually an expense.
If deducted upfront:
Long Example: Complete Loan Cycle (Realistic Scenario)
Let’s say:
-
Loan sanctioned: ₹5,00,000
-
Processing fee: ₹10,000
-
EMI: ₹15,000
-
Interest per EMI: ₹4,000
-
Principal per EMI: ₹11,000
1. Loan Sanctioned
2. Monthly EMI Payment
3. Interest Accrued at Month-End (If Not Paid Immediately)
Loan Journal Entry Format (Quick Template)
Use this anytime:
| Transaction | Debit | Credit |
|---|---|---|
| Loan Received | Bank/ Cash | Loan A/C |
| EMI Payment | Loan A/C + Interest Exp | Bank |
| Interest Accrued | Interest Exp | Interest Payable |
| Loan Prepaid | Loan A/C | Bank |
| Processing Fee | Processing Fee Exp | Bank |
Bookmark it mentally. Or print it and stick it somewhere.
Common Mistakes People Make (Please Avoid These)
1. Recording total EMI as principal
Happens surprisingly often.
2. Forgetting processing fees
Banks never forget fees — neither should you.
3. Ignoring accrued interest
You’ll get a shock later during audits.
4. Mixing up personal and business loans
Please don’t. Your books deserve better.
5. Incorrect liability classification
Short-term vs long-term matters.
Expert Insights: How to Keep Loan Entries Audit-Ready
After years of making mistakes (sometimes spectacular ones), here’s what I learned:
✔ Maintain a separate loan ledger
✔ Keep EMI breakup statements
✔ Reconcile interest quarterly
✔ Update accrued interest monthly
✔ Store all loan agreements digitally
✔ Automate with accounting software if possible
Honestly, investing 10 minutes a week saves hours during audit season.
FAQs (Optimized for Google Featured Snippets)
1. What is the journal entry for taking a loan?
Debit Bank A/C, Credit Loan A/C.
This records the increase in assets and liability.
2. What is the journal entry for loan repayment?
3. Is loan a debit or credit?
Loan is a credit because it represents a liability.
4. How do you record loan interest?
Debit Interest Expense, credit Interest Payable or Bank, depending on payment.
5. What is the entry for processing fees?
Debit Processing Fee Expense, credit Bank A/C.
6. Are loans assets or liabilities?
Loans received = liability
Loans given to others = asset
Final Thoughts (And a Little Motivation)
Loan journal entries may look scary, but once you understand the logic, it’s like watching a movie twice — everything suddenly makes sense.
Remember:
-
Don’t overthink.
-
Don’t skip interest entries.
-
And for heaven’s sake, don’t record the entire EMI as principal!
Whether you’re a student, freelancer, business owner, or someone trying to keep their books clean — you’ve now got the ultimate guide.