
Cracking the Code on Loan Limits: Don’t Let Numbers Derail Your Dream Home (or Next Big Purchase)
Hey there, dream-chaser! Picture this: You’re scrolling Zillow late at night, heart racing over that cozy bungalow with the white picket fence. You’ve crunched the numbers, saved like a squirrel prepping for winter, and then—bam!—you hit a wall called “loan limits.” Sound familiar? I’ve been there, staring at my screen in 2022, ready to buy my first place in a mid-sized town, only to learn my county’s FHA cap was $420,000 back then. Spoiler: I walked away frustrated but smarter. Today, let’s unpack loan limits like old pals over coffee—no jargon overload, just real talk on how these sneaky ceilings can make or break your 2025 home hunt or personal cash grab.
Honestly, loan limits aren’t some evil plot; they’re guardrails set by feds to keep lending sane amid skyrocketing home prices. Think of them as the bouncer at a club—only letting in what the economy can handle without a hangover. In 2025, with President Trump’s pro-housing push post-reelection, these limits bumped up nicely, giving folks like you more borrowing power. But here’s the kicker: Ignore them, and you’re shopping jumbo loans with jumbo headaches. Ready to dive in?
What the Heck Are Loan Limits, Anyway?
Loan limits are basically the max amount Uncle Sam (via agencies like FHA or VA) will back for your mortgage. Exceed ’em? You’re in jumbo territory—higher rates, bigger down payments, like upgrading from economy to first class without the miles.
By the way, they fluctuate yearly based on median home values, county by county. In low-cost spots, you’re golden with baseline numbers; hit high-cost areas like LA or NYC, and ceilings soar. It’s like real estate poker—know your table limits or fold early.
I remember advising a buddy in rural Ohio; his FHA limit was comfy at the floor level, letting him snag a fixer-upper without sweat. Urban warriors? Different story—those ceilings save the day (or force a reality check).
2025 FHA Loan Limits: First-Timer’s Best Friend
Let’s talk FHA, the forgiving loan for folks with credit dings or tiny savings. In 2025, the floor (most counties) sits at $524,225 for a single-family pad—up from last year’s $498,257. That’s breathing room for 80% of America!
High-cost areas? Ceiling’s $1,209,750 for one-unit homes, scaling to $2.3 million for quads. Alaska, Hawaii? Even wilder at up to $1.8 million. Pro tip: Plug your county into HUD’s lookup tool—it’s free and foolproof.
My own FHA flirtation taught me: These limits pair with just 3.5% down, but watch MIP (that monthly insurance fee). It’s like renting from yourself, but with equity building. Relatable win? A client couple stretched to a duplex under the triplex limit of $1,872,225 in SoCal—now they’re landlords by accident.
Quick FHA Breakdown by Property Type (2025 Floor)
-
Single-Family: $524,225 – Perfect for starter homes.
-
Duplex: $671,200 – House-hack heaven.
-
Triplex: $811,275 – Investor lite.
-
Fourplex: $1,008,300 – Max income potential.
Conforming Loan Limits: The Conventional Sweet Spot
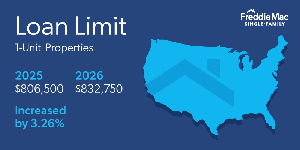
Shifting gears to conforming loans—Fannie Mae and Freddie Mac’s playground. Baseline for 2025? $806,500 for one-unit properties nationwide, a 5.2% jump thanks to home value spikes.
High-cost counties (think Seattle or Miami-Dade) climb to $1,209,750. Jumbo kicks in above that—think luxury pads where rates sting 0.5-1% more. Why care? Conforming means easier quals, lower rates—like the VIP line.
Fun fact from my lender days: A family in Phoenix hit the baseline exactly last year. This year’s bump? Let ’em upgrade without jumbo drama. Transitions like “but wait” matter—exceed it, and your DTI ratio screams uncle.
VA Loan Limits: Heroes Get Zero-Down Glory
Veterans, this one’s for you. VA loans ditched hard caps in 2020, but partial entitlement ties to county limits: $806,500 baseline, $1,209,750 high-cost.
Full entitlement? No limit—borrow what you qualify for, zero down. It’s like the military saying, “We got your six… and your down payment.” My Marine pal closed on a $950k Texas ranch under high-cost rules—no cash outlay. Epic.
Caveat: Lenders still eyeball your debt and reserves. Rhetorical Q: Why settle for less when Uncle Sam backs you unlimited?
USDA Loans: Rural Road to Homeownership
Dreaming of acreage? USDA’s your zero-down rural whisperer. No strict loan limits—instead, income caps rule: $119,850 for 1-4 person households, $158,250 for bigger crews in most spots.
High-cost rural? Limits flex higher. Eligibility’s picky—property must be USDA-approved zones. I helped a family flee city chaos to Georgia farmland; their income fit, loan sailed through. Metaphor alert: It’s the golden ticket for country mice, but check the map first.
Jumbo Loans: When Limits Say “No Mas”
Jumbos ignore caps—anything over conforming baselines. 2025 starts at $806,501, but lenders cap at $2-5M+ based on your wallet.
Expect 700+ credit, 20% down, reserves for a year’s payments. Humor break: It’s like dating a supermodel—gorgeous payoff, but picky and pricey. My luxury flip story? Overshot limits, paid premium rates—lesson learned.
Personal Loan Limits: Quick Cash, Smaller Stakes
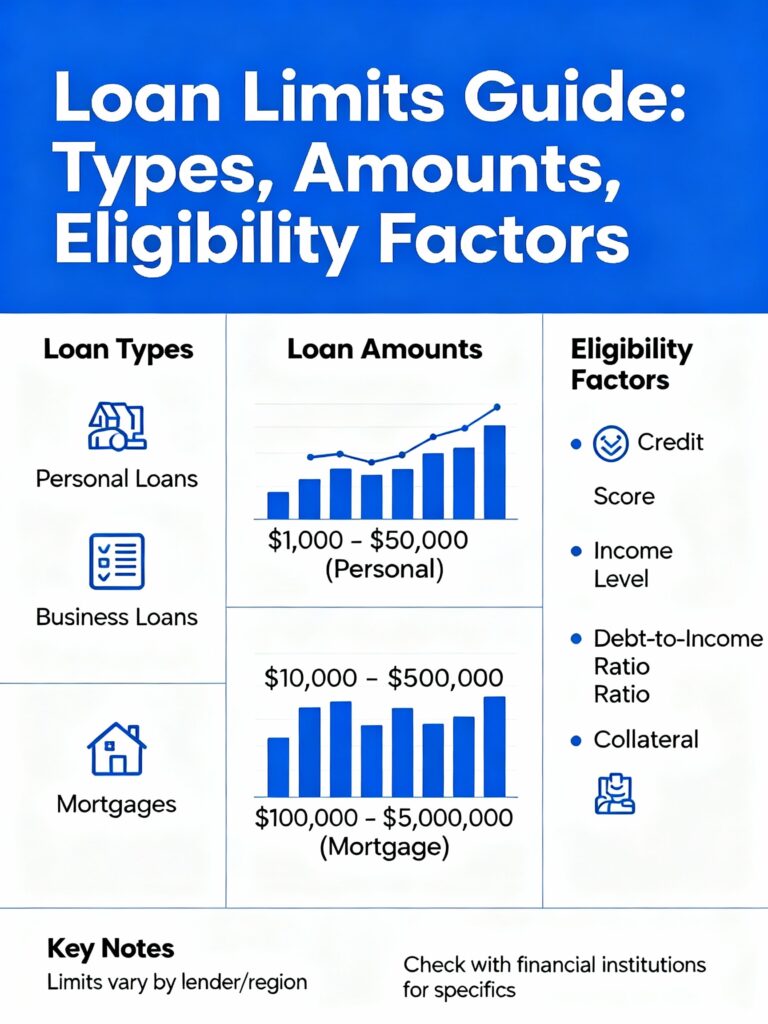
Not house-hunting? Personal loans top $50k average, with stars like LightStream hitting $100k.
Banks vary: U.S. Bank $50k, SoFi $100k. Credit’s king—good score unlocks max. Used mine once for a $20k reno; rates beat cards, but no collateral meant higher APR. Like a financial Band-Aid—handy, not heroic.
How Loan Limits Hit Your Wallet (Real Talk)
Limits shape everything. Under? Low rates, easy approval. Over? Jumbo surcharges add thousands yearly. Example: $900k home in baseline county—$93.5k down on jumbo vs. less on conforming nearby.
County matters hugely—NYC’s $1.2M vs. Buffalo’s $524k FHA. My anecdote: Advised a cross-state move to dodge limits, saved ’em 1% rate. Pro move.
2025 Loan Limits Cheat Sheet
| Loan Type | Baseline (Most Counties) | High-Cost Ceiling | Key Perk |
|---|---|---|---|
| FHA | $524,225 (1-unit) | $1,209,750 | 3.5% down |
| Conforming | $806,500 (1-unit) | $1,209,750 | Best rates |
| VA | No cap (full entitlement) | Ties to county | 0% down |
| USDA | Income-based (~no limit) | Varies | Rural 0% down |
| Jumbo | Over $806k+ | Lender max | Luxury buys |
| Personal | $10k-$50k avg | Up to $100k | Unsecured |
Busting Myths: Limits Aren’t Set in Stone
Myth 1: Limits = max you can borrow. Nope—qualifying’s the real boss.
Myth 2: All loans same limits. Wrong—FHA lower floor, VA limitless vibe.
Myth 3: Ignoring ’em saves cash. Ha! Higher rates bury you. From experience: Clients bypassing lookup tools regretted it big time.
Navigating Limits Like a Pro: Step-by-Step
-
Check Your County: HUD tool for FHA/VA—takes 30 seconds.
-
Run Numbers: Use calculators for DTI (aim <43%).
-
Shop Lenders: Rates vary 0.25%—shop three quotes.
-
Boost Quals: Pay debts, goose credit—unlocks more.
-
Consider Alt Loans: USDA if rural, VA if vet-eligible.
By the way, 2025’s hikes (5%+) stem from home prices up 5.2%—timing’s prime now.
FAQ: Your Burning Loan Limit Questions
What’s my county’s FHA limit? Use HUD’s lookup—2025 ranges $524k-$1.2M.
VA full entitlement no limit? Yes, zero-down uncapped if you qualify.
Jumbo vs conforming difference? Over $806k baseline = jumbo, tougher terms.
Personal loan max without collateral? $50k typical, $100k elite lenders.
Do limits change mid-year? Nope, annual Jan 1 reset.
Wrapping the Loan Limit Tango (With a Twist)
Whew, we’ve danced through digits, dodged pitfalls, and demystified the maze. Loan limits? They’re your map, not roadblocks—master ’em, and that dream home’s closer than yesterday’s coffee.
What’s your loan limit story? Dropped a house hunt bombshell? Spill in comments—I read every one. Better yet, grab HUD’s tool today and share your county surprise. Ready to chat your scenario? DM or comment—let’s turn limits into launches!